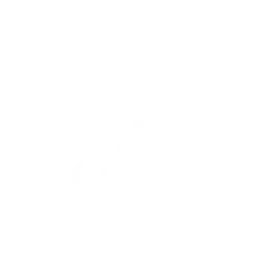
The index is a weighted blend of two 30-day volatilities, BTC's at 55% and ETH's at 45%. Each is the square root of the fair strike of a 30-day variance swap on that asset, computed by static replication over its out-of-the-money options on Deribit.
IV²₃₀ = (2/T) · Σᵢ (ΔKᵢ / Kᵢ²) · e^{rT} · Q(Kᵢ) − (1/T) · (F / K₀ − 1)²- T
- the expiry's time to maturity, in years
- F
- the expiry's forward: Deribit's underlying price for that expiry, not spot
- K₀
- first strike at or below F
- ΔKᵢ
- (Kᵢ₊₁ − Kᵢ₋₁) / 2; one-sided at the ends of a wing
- Q(Kᵢ)
- mid of the OTM option at Kᵢ, or its one quoted side; calls above F, puts at or below
- r
- taken as zero, so e^{rT} is 1
Constant-maturity interpolation
Listed expiries drift toward the front. The two expiries either side of the 30-day point are blended in total variance (σ²T), weighted by how far each sits from the target, so the published number always describes exactly 30 days of forward volatility. Expiries less than an hour from settlement are skipped, and when 30 days falls outside the listed range the closest pair is extrapolated.
Hygiene rules applied before replication
- Quotes with a zero bid are skipped, and each wing stops at its second consecutive zero bid, walking outward from the money.
- Quotes whose spread is wider than 150% of their mid are excluded rather than mid-marked.
- An expiry left with fewer than three strikes is not used.
- A surface that does not answer, or is too thin to replicate, is left out of that round and the other carries the whole index; a round with neither writes no index.
- The result is clamped by the dampener before it can reach settlement.